Business Today

business-today-logo
SUBSCRIPTION
ADVERTISE
Menu
  • Home
  • Issues
    • 1996 to 1999
      • 1996
        • May 1996
        • June 1996
        • July 1996
        • August 1996
        • September 1996
        • October 1996
        • November 1996
        • December 1996
      • 1997
        • January 1997
        • FEBRUARY 1997
        • March 1997
        • April 1997
        • May 1997
        • June 1997
        • July 1997
        • August 1997
        • September 1997
        • October 1997
        • November 1997
        • December 1997
    • 2000 to 2009
      • 2006
        • January 2006
        • February 2006
        • March 2006
        • April 2006
        • May 2006
        • June 2006
        • July 2006
        • August 2006
        • September 2006
        • October 2006
        • November 2006
        • December 2006
      • 2007
        • January 2007
        • February 2007
        • March 2007
        • April 2007
        • May 2007
        • July 2007
        • June 2007
        • August 2007
        • September 2007
        • October 2007
        • November 2007
        • December 2007
      • 2008
        • January 2008
        • February 2008
        • March 2008
        • May 2008
        • April 2008
        • June 2008
        • July 2008
        • August 2008
        • September 2008
        • November 2008
        • October 2008
        • December 2008
      • 2009
        • January 2009
        • February 2009
        • March 2009
        • April 2009
        • May 2009
        • June 2009
        • July 2009
        • August 2009
        • September 2009
        • October 2009
        • November 2009
        • December 2009
    • 2010 to 2019
      • 2010
        • January 2010
        • February 2010
        • March 2010
        • April 2010
        • May 2010
        • June 2010
        • July 2010
        • August 2010
        • September 2010
        • October 2010
        • November 2010
        • December 2010
      • 2011
        • January 2011
        • February 2011
        • March 2011
        • April 2011
        • May 2011
        • June 2011
        • July 2011
        • August 2011
        • September 2011
        • October 2011
        • November 2011
        • December 2011
      • 2012
        • January 2012
        • February 2012
        • March 2012
        • April 2012
        • May 2012
        • June 2012
        • July 2012
        • August 2012
        • September 2012
        • October 2012
        • November 2012
        • December 2012
      • 2013
        • January 2013
        • February 2013
        • March 2013
        • April 2013
        • May 2013
        • June 2013
        • July 2013
        • August 2013
        • September 2013
        • October 2013
        • November 2013
        • December 2013
      • 2014
        • January 2014
        • February 2014
        • March 2014
        • April 2014
        • May 2014
        • June 2014
        • July 2014
        • August 2014
        • September 2014
        • October 2014
        • November 2014
        • December 2014
      • 2015
        • January 2015
        • February 2015
        • March 2015
        • April 2015
        • May 2015
        • June 2015
        • July 2015
        • August 2015
        • September 2015
        • October 2015
        • November 2015
        • December 2015
      • 2016
        • January 2016
        • February 2016
        • March 2016
        • April 2016
        • May 2016
        • June 2016
        • July 2016
        • August 2016
        • September 2016
        • October 2016
        • November 2016
        • December 2016
      • 2017
        • January 2017
        • February 2017
        • March 2017
        • April 2017
        • May 2017
        • June 2017
        • July 2017
        • August 2017
        • September 2017
        • October 2017
        • November 2017
        • December 2017
      • 2018
        • January 2018
        • February 2018
        • March 2018
        • April 2018
        • May 2018
        • August 2018
        • June 2018
        • July 2018
        • September 2018
        • October 2018
        • November 2018
        • December 2018
      • 2019
        • January 2019
        • February 2019
        • March 2019
        • April 2019
        • May 2019
        • June 2019
        • July 2019
        • August 2019
        • September 2019
        • October 2019
        • November 2019
        • December 2019
    • 2020 to 2025
      • 2020
        • January 2020
        • February 2020
        • March 2020
        • April 2020
        • May 2020
        • June 2020
        • July 2020
        • August 2020
        • September 2020
        • October 2020
        • November 2020
        • December 2020
      • 2021
        • September 2021
        • October 2021
      • 2022
        • January 2022
        • February 2022
        • March 2022
        • April 2022
        • May 2022
        • June 2022
        • July 2022
        • August 2022
        • September 2022
        • October 2022
        • December 2022
      • 2023
        • January 2023
        • February 2023
        • March 2023
        • April 2023
        • May 2023
        • June 2023
        • July 2023
        • August 2023
        • September 2023
        • October 2023
        • November 2023
        • December 2023
      • 2024
        • January 2024
        • February 2024
        • March 2024
        • April 2024
        • May 2024
        • June 2024
        • July 2024
        • August 2024
        • September 2024
        • October 2024
        • November 2024
        • December 2024
      • 2025
        • January 2025
        • February 2025
        • March 2025
        • April 2025
        • May 2025
        • June 2025
        • July 2025
        • August 2025
        • September 2025
        • October 2025
        • November 2025
        • December 2025
      • 2026
        • January 2026
        • February 2026
        • March 2026
        • April 2026
        • May 2026
        • June 2026
        • July 2026
        • August 2026
        • September 2026
  • About Us
  • BT Awards
    • BT Top 40
      • Business Today Top 40 2021 – 2022
    • BT Top 30
      • Business Today Top 30 2015 – 2016
      • Business Today Top 30 2016 – 2017
      • Business Today Top 30 2017 – 2018
      • Business Today Top 30 2018 – 2019
    • BT Top 25
      • Business Today Top 25 2011 – 2012
      • Business Today Top 25 2012 – 2013
      • Business Today Top 25 2013 – 2014
      • Business Today Top 25 2014 – 2015
    • BT Top 20
      • Business Today Top 20 2009 – 2010
      • Business Today Top 20 2010 – 2011
    • BT Top 10
      • Business Today Top 10 2008 – 2009
      • Business Today Top 10 2007 – 2008
      • Business Today Top 10 2006 – 2007
      • Business Today Top 10 2005 – 2006
      • Business Today Top 10 2003 – 2004
      • Business Today Top 10 2000 – 2001
      • Business Today Top 10 1999 – 2000
      • Business Today Top 10 1997 – 1998
      • Business Today Top 10 1996 – 1997
      • Business Today Top 10 1995 – 1996
  • Digital Subscription
  • Digital Copy
Facebook Instagram
business-today-logo
Menu
  • Home
  • Issues
    • 1996 to 1999
      • 1996
        • May 1996
        • June 1996
        • July 1996
        • August 1996
        • September 1996
        • October 1996
        • November 1996
        • December 1996
      • 1997
        • January 1997
        • FEBRUARY 1997
        • March 1997
        • April 1997
        • May 1997
        • June 1997
        • July 1997
        • August 1997
        • September 1997
        • October 1997
        • November 1997
        • December 1997
    • 2000 to 2009
      • 2006
        • January 2006
        • February 2006
        • March 2006
        • April 2006
        • May 2006
        • June 2006
        • July 2006
        • August 2006
        • September 2006
        • October 2006
        • November 2006
        • December 2006
      • 2007
        • January 2007
        • February 2007
        • March 2007
        • April 2007
        • May 2007
        • July 2007
        • June 2007
        • August 2007
        • September 2007
        • October 2007
        • November 2007
        • December 2007
      • 2008
        • January 2008
        • February 2008
        • March 2008
        • May 2008
        • April 2008
        • June 2008
        • July 2008
        • August 2008
        • September 2008
        • November 2008
        • October 2008
        • December 2008
      • 2009
        • January 2009
        • February 2009
        • March 2009
        • April 2009
        • May 2009
        • June 2009
        • July 2009
        • August 2009
        • September 2009
        • October 2009
        • November 2009
        • December 2009
    • 2010 to 2019
      • 2010
        • January 2010
        • February 2010
        • March 2010
        • April 2010
        • May 2010
        • June 2010
        • July 2010
        • August 2010
        • September 2010
        • October 2010
        • November 2010
        • December 2010
      • 2011
        • January 2011
        • February 2011
        • March 2011
        • April 2011
        • May 2011
        • June 2011
        • July 2011
        • August 2011
        • September 2011
        • October 2011
        • November 2011
        • December 2011
      • 2012
        • January 2012
        • February 2012
        • March 2012
        • April 2012
        • May 2012
        • June 2012
        • July 2012
        • August 2012
        • September 2012
        • October 2012
        • November 2012
        • December 2012
      • 2013
        • January 2013
        • February 2013
        • March 2013
        • April 2013
        • May 2013
        • June 2013
        • July 2013
        • August 2013
        • September 2013
        • October 2013
        • November 2013
        • December 2013
      • 2014
        • January 2014
        • February 2014
        • March 2014
        • April 2014
        • May 2014
        • June 2014
        • July 2014
        • August 2014
        • September 2014
        • October 2014
        • November 2014
        • December 2014
      • 2015
        • January 2015
        • February 2015
        • March 2015
        • April 2015
        • May 2015
        • June 2015
        • July 2015
        • August 2015
        • September 2015
        • October 2015
        • November 2015
        • December 2015
      • 2016
        • January 2016
        • February 2016
        • March 2016
        • April 2016
        • May 2016
        • June 2016
        • July 2016
        • August 2016
        • September 2016
        • October 2016
        • November 2016
        • December 2016
      • 2017
        • January 2017
        • February 2017
        • March 2017
        • April 2017
        • May 2017
        • June 2017
        • July 2017
        • August 2017
        • September 2017
        • October 2017
        • November 2017
        • December 2017
      • 2018
        • January 2018
        • February 2018
        • March 2018
        • April 2018
        • May 2018
        • August 2018
        • June 2018
        • July 2018
        • September 2018
        • October 2018
        • November 2018
        • December 2018
      • 2019
        • January 2019
        • February 2019
        • March 2019
        • April 2019
        • May 2019
        • June 2019
        • July 2019
        • August 2019
        • September 2019
        • October 2019
        • November 2019
        • December 2019
    • 2020 to 2025
      • 2020
        • January 2020
        • February 2020
        • March 2020
        • April 2020
        • May 2020
        • June 2020
        • July 2020
        • August 2020
        • September 2020
        • October 2020
        • November 2020
        • December 2020
      • 2021
        • September 2021
        • October 2021
      • 2022
        • January 2022
        • February 2022
        • March 2022
        • April 2022
        • May 2022
        • June 2022
        • July 2022
        • August 2022
        • September 2022
        • October 2022
        • December 2022
      • 2023
        • January 2023
        • February 2023
        • March 2023
        • April 2023
        • May 2023
        • June 2023
        • July 2023
        • August 2023
        • September 2023
        • October 2023
        • November 2023
        • December 2023
      • 2024
        • January 2024
        • February 2024
        • March 2024
        • April 2024
        • May 2024
        • June 2024
        • July 2024
        • August 2024
        • September 2024
        • October 2024
        • November 2024
        • December 2024
      • 2025
        • January 2025
        • February 2025
        • March 2025
        • April 2025
        • May 2025
        • June 2025
        • July 2025
        • August 2025
        • September 2025
        • October 2025
        • November 2025
        • December 2025
      • 2026
        • January 2026
        • February 2026
        • March 2026
        • April 2026
        • May 2026
        • June 2026
        • July 2026
        • August 2026
        • September 2026
  • About Us
  • BT Awards
    • BT Top 40
      • Business Today Top 40 2021 – 2022
    • BT Top 30
      • Business Today Top 30 2015 – 2016
      • Business Today Top 30 2016 – 2017
      • Business Today Top 30 2017 – 2018
      • Business Today Top 30 2018 – 2019
    • BT Top 25
      • Business Today Top 25 2011 – 2012
      • Business Today Top 25 2012 – 2013
      • Business Today Top 25 2013 – 2014
      • Business Today Top 25 2014 – 2015
    • BT Top 20
      • Business Today Top 20 2009 – 2010
      • Business Today Top 20 2010 – 2011
    • BT Top 10
      • Business Today Top 10 2008 – 2009
      • Business Today Top 10 2007 – 2008
      • Business Today Top 10 2006 – 2007
      • Business Today Top 10 2005 – 2006
      • Business Today Top 10 2003 – 2004
      • Business Today Top 10 2000 – 2001
      • Business Today Top 10 1999 – 2000
      • Business Today Top 10 1997 – 1998
      • Business Today Top 10 1996 – 1997
      • Business Today Top 10 1995 – 1996
  • Digital Subscription
  • Digital Copy

Who Controls Tata?

by
Reading Time: 12 mins read
0
Share on Twitter
PDF Button


Words: Arvind Rayan.
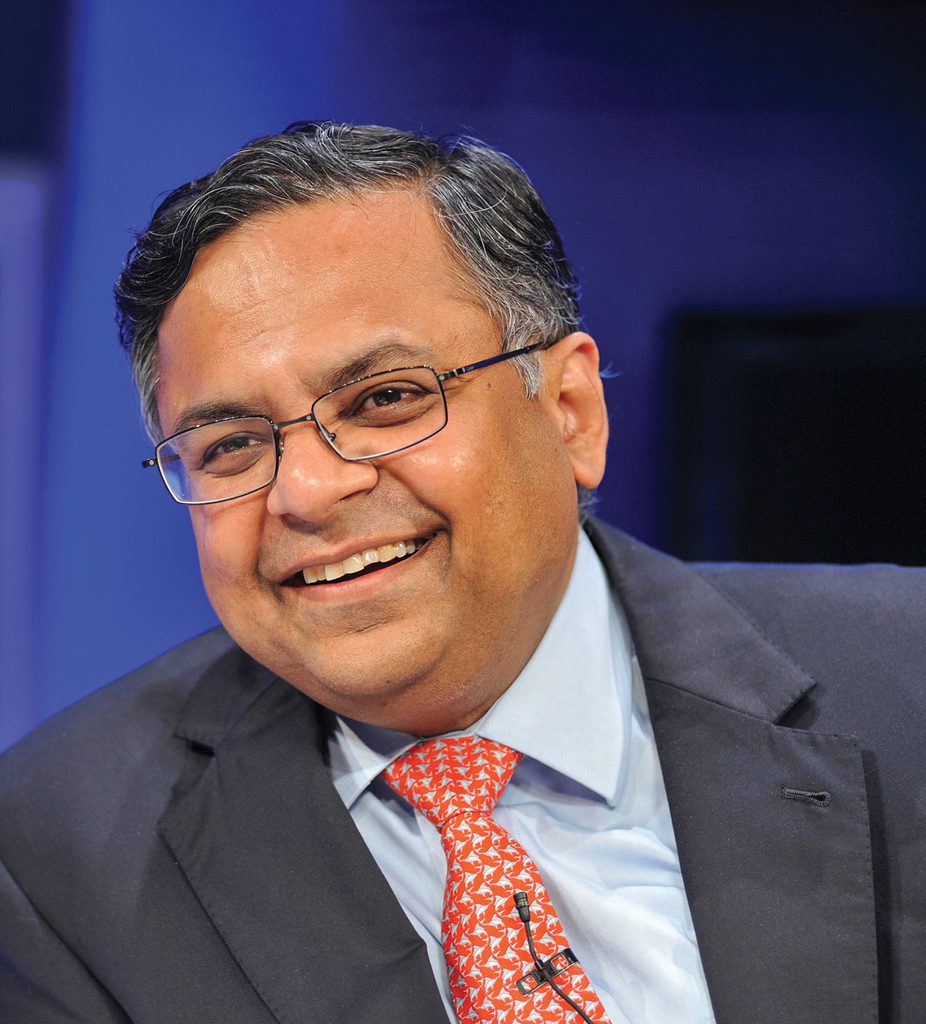

N. Chandrasekaran, Chairman of Tata Sons. After his August decision not to seek another term, developments in September dramatically reopened the question of his future at the helm of the Tata Group.

What began in August as the impending departure of Natarajan Chandrasekaran from Tata Sons has, within a matter of weeks, become considerably more consequential. The question is no longer simply who will succeed one of India’s most powerful corporate leaders. Tata is confronting a fundamental argument over authority, the board’s power, the controlling shareholder’s rights, the future of Tata Sons as a private company, and, ultimately, the manner in which India’s most celebrated corporate institution should be governed in the post-Ratan Tata era.
Mr. Noel Tata and Mr. Philip Clarke, CEO, Tesco meeting the Union Minister for Commerce & Industry and Textiles, Shri Anand Sharma, in New Delhi on May 10, 2013.

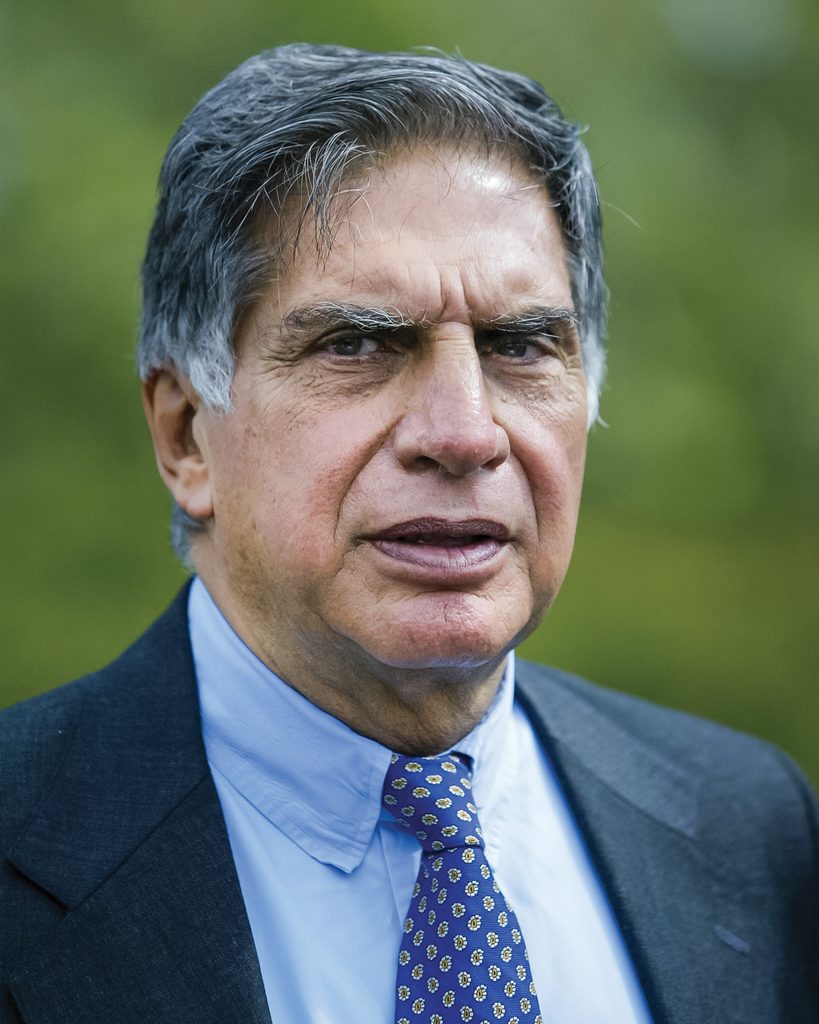
Ratan Tata provided an extraordinary degree of institutional cohesion across the Tata universe. The post-Ratan era is testing whether formal governance structures can provide the same continuity.
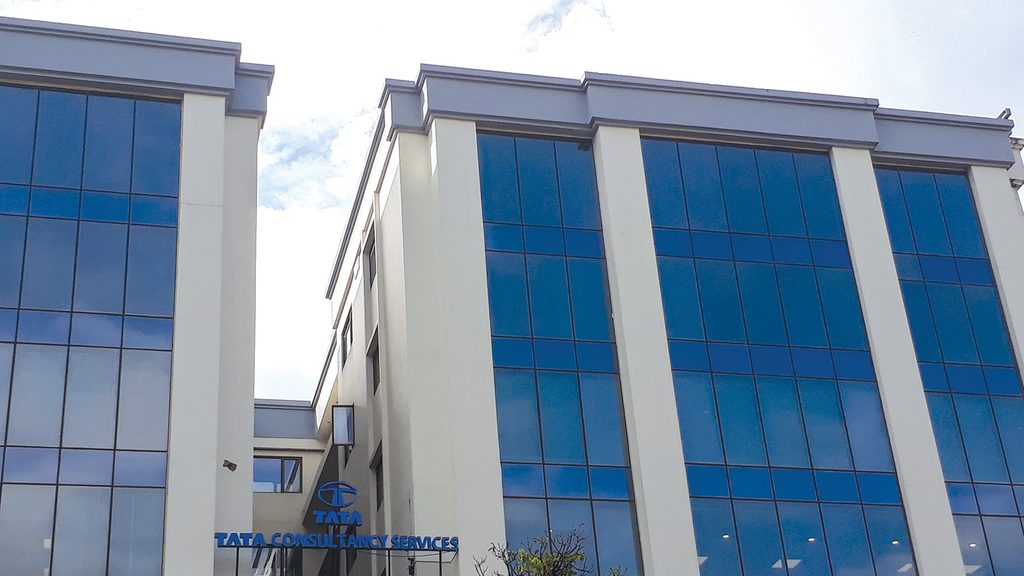

Tata Consultancy Services, Varanasi.

On August 12, 2026, Chandrasekaran informed the Tata Sons board that he would not offer himself for reappointment after his existing term expires on February 20, 2027. At that point, Tata appeared to be entering a difficult but manageable succession process. A selection mechanism could be activated, candidates evaluated, and a new chairman chosen to inherit a conglomerate whose businesses span information technology and automobiles, steel, aviation, power, hotels, consumer products, financial services, electronics, and semiconductors. By September, however, that apparently straightforward sequence had been overturned.

At a Tata Sons board meeting on September 17, Chandrasekaran’s continuation returned to the agenda. The board voted 4-1 in favor of giving him another five-year term. Tata Trusts Chairman Noel Tata, one of the Trust-nominated directors on the Tata Sons board, opposed the resolution, while the other Trust-nominated director, Venu Srinivasan, supported it. Ordinarily, a 4-1 board vote might appear decisive. At Tata Sons, however, the matter is complicated by provisions in the company’s Articles of Association and by the special position occupied by Tata Trusts, which collectively control approximately 66 percent of Tata Sons. Tata Trusts maintains that the resolution did not satisfy a separate requirement contained in Tata Sons’ Articles of Association. Its position is that certain board decisions require not merely an overall board majority but also the affirmative support of a majority of the directors nominated by Tata Trusts. With the two Trust nominees divided, Tata Trusts argues that the necessary approval was not obtained. Tata Sons disputes that conclusion and maintains that the board acted within the applicable legal and governance framework. The competing interpretations have consequently transformed what began as a succession question into a potentially significant corporate governance dispute. Until the matter is resolved through agreement or authoritative legal determination, neither interpretation should be treated as the definitive legal position.

The dispute is much larger than Chandrasekaran himself. At stake is the constitutional relationship between Tata Sons and Tata Trusts. Tata Sons is the principal investment holding company and promoter of the Tata Group, while Tata Trusts is its controlling shareholder. Yet Tata Sons has its own board, directors, and corporate responsibilities. The disagreement, therefore, raises one of the oldest and most difficult questions in corporate governance. Where does the legitimate authority of a board end and the rights of a controlling shareholder begin?

For most corporations, that would already constitute a substantial governance issue. For Tata, there is another dimension: the controlling shareholder is not a conventional billionaire family holding company or an institutional investor. Tata Trusts represents the philanthropic architecture at the center of the Tata model. The commercial success of the Tata empire ultimately supports charitable activity on an enormous scale. This unusual combination of capitalism and philanthropy has helped give Tata a reputation extending far beyond the financial value of its companies. Preserving that distinctive structure is therefore more than an ownership question. It concerns Tata’s identity.

A second major issue concerns whether Tata Sons should eventually be listed on the stock exchange. The question had hovered over the group for years, but it became considerably more urgent in September, when the Reserve Bank of India rejected Tata Sons’ request to surrender its registration as a core investment company and directed it to comply with the regulatory framework applicable to it. The regulatory position is complicated, but the strategic consequence is unmistakable. Pressure surrounding the future status and possible listing of Tata Sons has intensified. For Tata Trusts, this cannot be viewed simply as an initial public offering. A public listing could fundamentally change the environment in which Tata Sons operates. A privately controlled holding company can take an exceptionally long view of capital, strategy, and philanthropy. A listed company must also contend with market valuations, disclosure obligations, public shareholders, and the expectations accompanying participation in public capital markets. The Trust’s preference has been to explore alternatives that would allow Tata Sons to remain unlisted, reflecting its concern with preserving an institutional model that has developed over generations.

The opposing economic pressure is equally formidable. The Shapoorji Pallonji Group, which owns approximately 18.4 percent of Tata Sons and is its largest shareholder after Tata Trusts, has supported a listing. For the SP Group, the question carries enormous financial significance because its Tata Sons shareholding represents a substantial concentration of value.

A publicly traded Tata Sons could provide market-based price discovery and potentially greater liquidity for that holding. Tata Trusts has also explored possibilities that could provide liquidity for part of the SP Group’s stake without necessarily requiring Tata Sons itself to proceed immediately towards a public listing.

The Tata question has consequently become a three-dimensional problem involving professional management, the controlling shareholder, and the largest minority shareholder. Each has legitimate interests. Tata Sons requires sufficient managerial and board authority to operate one of the world’s largest and most diversified corporate groups. Tata Trusts, as the owner of roughly two-thirds of Tata Sons, has substantial shareholder rights and a responsibility to protect the philanthropic structure associated with the Tata legacy. The SP Group has a legitimate economic interest in the value and liquidity of its minority holding. Reconciling all three interests would test even the most sophisticated governance system.

The timing makes the confrontation particularly sensitive because Tata is already attempting some of the most ambitious industrial transformations in its history. Air India is undergoing a massive rebuilding program. Tata is investing in semiconductor manufacturing and electronics. Battery production, electric mobility, renewable energy, digital businesses, and advanced manufacturing all require significant capital. Tata Consultancy Services is navigating an information technology industry being reshaped by artificial intelligence. Jaguar Land Rover operates within a global automotive market undergoing enormous technological and competitive change. Decisions made at Tata Sons, therefore, have implications that stretch far beyond Bombay House.

Chandrasekaran’s supporters can point to the extraordinary transformation that has occurred during his tenure. He took over Tata Sons in 2017 following the deeply disruptive removal of Cyrus Mistry and helped restore institutional stability. Tata Motors subsequently underwent a remarkable recovery. Jaguar Land Rover emerged from periods of severe financial stress. Tata established a major position in India’s electric vehicle market. Indian Hotels accelerated its expansion. Tata Electronics emerged as a strategic manufacturing platform. Air India returned to Tata ownership. The group entered semiconductor manufacturing on a scale few Indian companies could contemplate. Tata has become more ambitious, more technologically focused, and more willing to make investments intended to produce returns over very long periods.

That ambition inevitably creates another source of tension because ambition requires capital. Aviation requires enormous capital. Semiconductor manufacturing requires enormous capital. Batteries, electric vehicles, electronics, renewable energy, and digital platforms all require investment before mature returns materialize. A group pursuing several of these transformations simultaneously must confront difficult questions about capital allocation, execution risk, and how long shareholders should be prepared to wait before investments produce sustainable returns.

These are legitimate subjects for disagreement between boards, management, and shareholders. The existence of disagreement does not necessarily imply that an institution is dysfunctional. In healthy corporations, disagreement is precisely what governance mechanisms are designed to accommodate. The problem begins when the parties disagree not only about the decision but also about who possesses the authority to make it. That is why the September confrontation is so significant. Tata Trusts’ challenge to Chandrasekaran’s reappointment concerns the interpretation of Tata Sons’ constitutional arrangements. Tata Sons’ defense of the board decision concerns the authority of its directors to govern the company. The listing debate concerns regulators, shareholders, and the future structure of the holding company. The SP Group’s position introduces minority shareholder rights and liquidity into the equation. Almost every road now leads back to governance.

There is an uncomfortable historical echo. A decade ago, the removal of Cyrus Mistry as Chairman of Tata Sons produced one of the most dramatic corporate disputes India had witnessed. The confrontation eventually reached the Supreme Court, placing Tata’s Articles of Association, the rights of the Tata Trusts, and the authority of the Tata Sons board under intense scrutiny. The circumstances today are very different, and it would be misleading to treat Chandrasekaran’s situation as a repetition of the Mistry conflict. Chandrasekaran has led Tata through almost a decade of substantial growth and strategic expansion, and the present disagreement concerns different circumstances. Yet the institutional question has returned. How should power be balanced between Tata Sons and Tata Trusts?

Ratan Tata’s presence once provided a degree of cohesion that formal structures alone could never entirely reproduce. His authority came from history, ownership relationships, personal standing, and decades of association with the group. He could occupy several dimensions of the Tata universe simultaneously in a manner that no ordinary corporate chairman could replicate. His death in October 2024 changed that equation permanently. Noel Tata’s subsequent appointment as Chairman of Tata Trusts gave the philanthropic side of the Tata establishment a new leader, while Chandrasekaran remained at the helm of Tata Sons. Consequently, the effectiveness of the post Ratan-Tata structure depended heavily on the institutional alignment between the controlling shareholder and the holding company’s professional leadership.

The events of 2026 demonstrate how difficult that transition can be. It would nevertheless be simplistic to describe the present situation merely as a personal contest between Noel Tata and Chandrasekaran. That interpretation may produce dramatic headlines, but it understates the structural nature of the problem. Even if both men disappeared from the equation tomorrow, Tata would still need to determine the powers of the Trusts, the autonomy of the Tata Sons board, the future ownership structure of Tata Sons, the rights of minority shareholders, and the mechanism through which future chairmen are appointed. These are institutional questions rather than personality questions.

The most important outcome of the present confrontation may therefore be a clearer definition of the Tata constitution for the twenty-first century. Can a Tata Sons board make a fundamental leadership decision when the Tata Trusts-nominated directors are divided? How should provisions granting particular rights to Trust nominees operate when only two such nominees sit on the board? What role should Tata Trusts play in decisions affecting the holding company’s structure? How should Tata balance the desire to remain privately controlled against regulatory requirements? What mechanism could provide liquidity to a major minority shareholder without undermining the architecture that the Trusts seek to preserve? These questions have moved from the background of Tata governance to its very center.
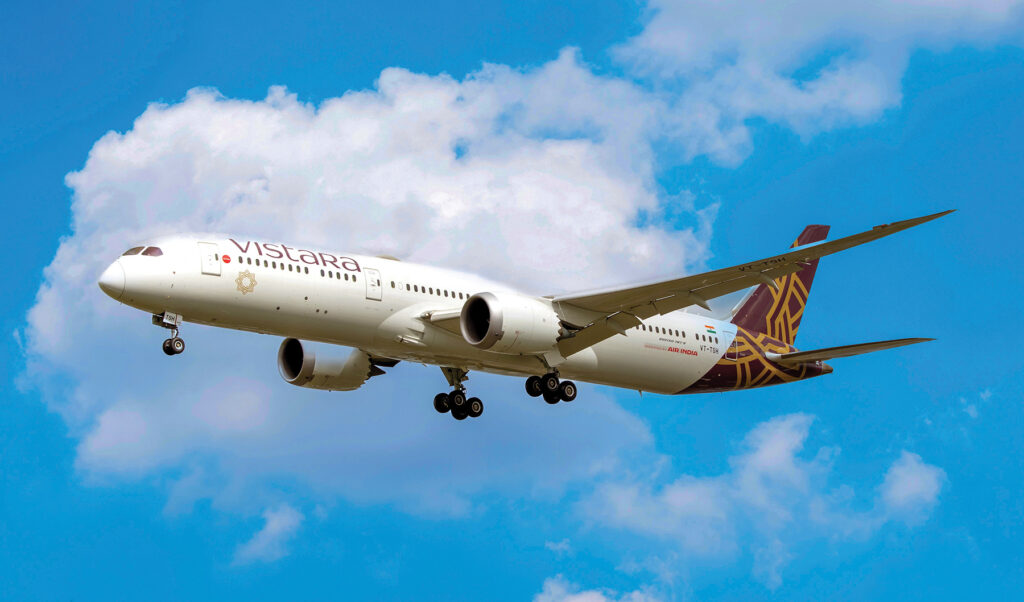
A Vistara aircraft takes to the skies, representing Tata Group’s presence in India’s aviation sector.


There is another issue that corporate leaders around the world should watch carefully. How much independence should a professional chairman possess when the controlling shareholder has objectives extending beyond conventional financial returns? The Tata model deliberately contains a tension between commerce and trusteeship. Tata Sons must compete aggressively in global markets, while Tata Trusts exists principally for philanthropic purposes. The profits generated by the commercial system ultimately help support a broader social mission. That arrangement is one of Tata’s greatest strengths, but it means conventional assumptions about shareholder value cannot fully capture the institution’s purpose.

A public listing could make that tension even more visible. Public shareholders would naturally expect financial performance, transparency, and appropriate returns. Tata Trusts would remain concerned with preserving the philanthropic philosophy and the group’s long-term stewardship. Professional management would require sufficient freedom to undertake investments whose economics might unfold over decades rather than quarters. The governance challenge would be formidable. The SP Group’s presence makes the question even more complex because its substantial minority holding cannot simply be ignored, while any solution involving Tata Sons’ ownership could have implications for the Trusts’ controlling position and the wider Tata model.

The debate is therefore not about whether an initial public offering is intrinsically good or bad. It is about what Tata Sons is supposed to be. Is it principally the privately held apex institution of a philanthropically controlled corporate group? Is it a commercial holding company that should eventually operate under the disciplines of public markets? Can it become both without fundamentally changing Tata’s character? If it does eventually list, can the philanthropic ownership philosophy that has distinguished Tata for generations remain intact? These questions require careful consideration rather than ideological answers.

For Chandrasekaran, the September board decision has produced an extraordinary reversal. In August, the corporate world was preparing for the end of his tenure. By September, a majority of the Tata Sons board had voted to reappoint him for another five years, yet the controlling shareholder disputes the validity of that decision. India’s most important corporate succession has consequently become highly unusual. A chairman’s continuation has received the support of a board majority but is being contested on the grounds of governance rights asserted by the majority shareholder.
Tata Steel, Jamshedpur.

The eventual resolution will matter well beyond Tata. Indian corporations are increasingly global institutions, and their governance structures must withstand scrutiny from international investors, lenders, regulators, employees, governments, and strategic partners. Tata occupies a particularly important place in that discussion because of its scale and reputation. The manner in which it resolves a disagreement involving board authority and shareholder rights will inevitably be studied as a significant case in corporate governance.

There is also a reputational dimension that cannot be ignored. Tata’s most valuable asset may not appear anywhere on a balance sheet. It is trust. For generations of Indians, the Tata name has represented a particular conception of capitalism, commercially ambitious but institutionally restrained, enormously powerful but closely associated with philanthropy, and capable of competing globally while retaining a distinctive social identity. Internal disagreement does not destroy that reputation because mature institutions inevitably disagree. The manner in which disagreement is resolved, however, matters enormously.

A prolonged legal or institutional confrontation could create uncertainty at precisely the moment when Tata requires strategic concentration. Air India’s transformation will not wait for a governance disagreement to conclude. Semiconductor factories will not build themselves. The transition towards electric mobility will continue. Artificial intelligence will continue to transform the technology industry. Global competitors will not suspend their strategies while Tata determines its internal balance of authority. That is why reconciliation, or at a minimum a clear institutional resolution, is important for the wider group.

The strongest outcome would not necessarily be one in which Tata Sons defeats Tata Trusts or Tata Trusts defeats Tata Sons. Such a framing misunderstands the nature of the institution. The Trust owns Tata Sons, which sits at the center of the commercial system that sustains the Trust’s philanthropic capacity. Their long-term interests ultimately intersect even when their immediate positions differ. The challenge is to rediscover and formally define that intersection in a way that can survive future disagreements.

For CEOs and corporate boards, Tata’s experience provides a powerful lesson about succession. Selecting a leader is only one part of succession planning. The institution must also define the powers attached to the office, the relationship between the executive and controlling shareholders, the process for resolving disagreements, and the circumstances under which authority can be challenged. Without that clarity, even the appointment of an exceptionally successful executive can become contested.

There is an equally important lesson for family-controlled and foundation-controlled businesses. Professionalization is not achieved merely by appointing professional managers. Genuine professionalization requires shareholders to define how much authority those managers possess and then create mechanisms for holding them accountable without continuously undermining that authority. Conversely, professional managers cannot treat shareholder rights as an inconvenience. Ownership matters. A shareholder controlling approximately two-thirds of a company cannot realistically be regarded as an ordinary investor whose views become relevant only at annual meetings. Finding the appropriate balance is the essence of governance.

Tata now has an opportunity to define that balance more clearly than at almost any point in its modern history. The immediate questions are formidable. Does Chandrasekaran begin another five-year term after February 2027? Can Tata Sons and Tata Trusts reach a common interpretation of the Articles of Association? Will the disagreement eventually require an authoritative legal determination? Can Tata Sons find a regulatory route that allows it to remain private, or will the pressure towards a listing continue to intensify? Can the SP Group obtain meaningful liquidity without destabilizing the existing ownership structure? The answers could shape the Tata Group for decades.

October 2026, therefore, finds Tata in a dramatically different position from only two months earlier. In August, the central question appeared to be who would replace Chandrasekaran. By late September, the question had become whether he was leaving at all. Even that, however, understates the significance of what is happening. The deeper question is who ultimately possesses the authority to decide, and how that authority should be exercised, when the board of Tata Sons and its controlling shareholder do not share the same interpretation of a fundamental corporate decision.

For a corporate house founded in 1868 and built with the intention of enduring beyond individual generations, the answer will shape far more than the tenure of a single chairman. It could determine how Tata balances ownership, professional management, philanthropy, minority shareholder interests, and public accountability for decades to come. The next chapter of the Tata story is therefore no longer simply about succession. It is about whether one of the world’s most distinctive corporate structures can adapt its governance to the post-Ratan Tata era while preserving the institutional character that made Tata different in the first place.

The chairman matters. The board matters. The Trusts matter. The shareholders matter. But ultimately, the institution must matter more than all of them.
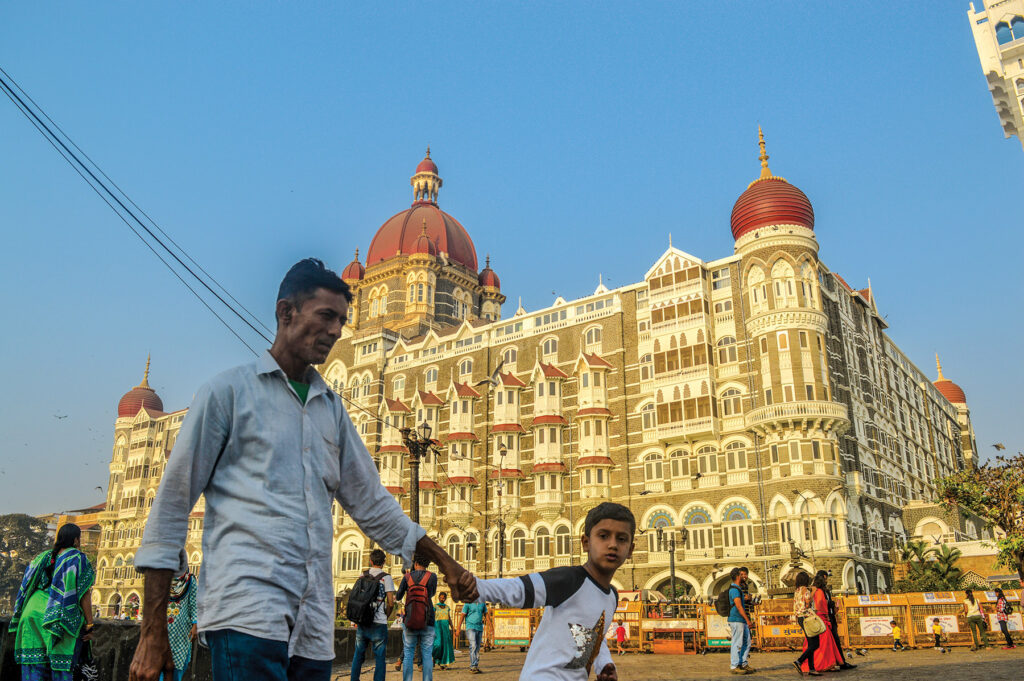
The iconic Taj Mahal Palace in Mumbai, part of Indian Hotels Company, Tata Group’s hospitality business.
Tags: October 2026Tata

Related Posts

Nimal Cooke: Creating Businesses That Matter
October 2026

Nimal Cooke: Creating Businesses That Matter

Beyond Connectivity
October 2026

Beyond Connectivity

The Next Development Mandate
October 2026

The Next Development Mandate

business-today-logo

Location

20-2/1 Lauries Place Facing R A de Mel Mawatha Colombo 04.

Contact

+94 715 134 134

Email

info@btoptions.com

© 2026 BT Options. All Rights Reserved.