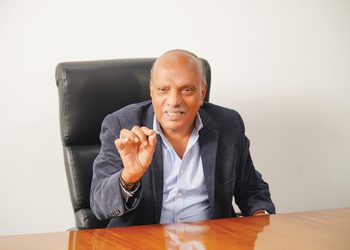
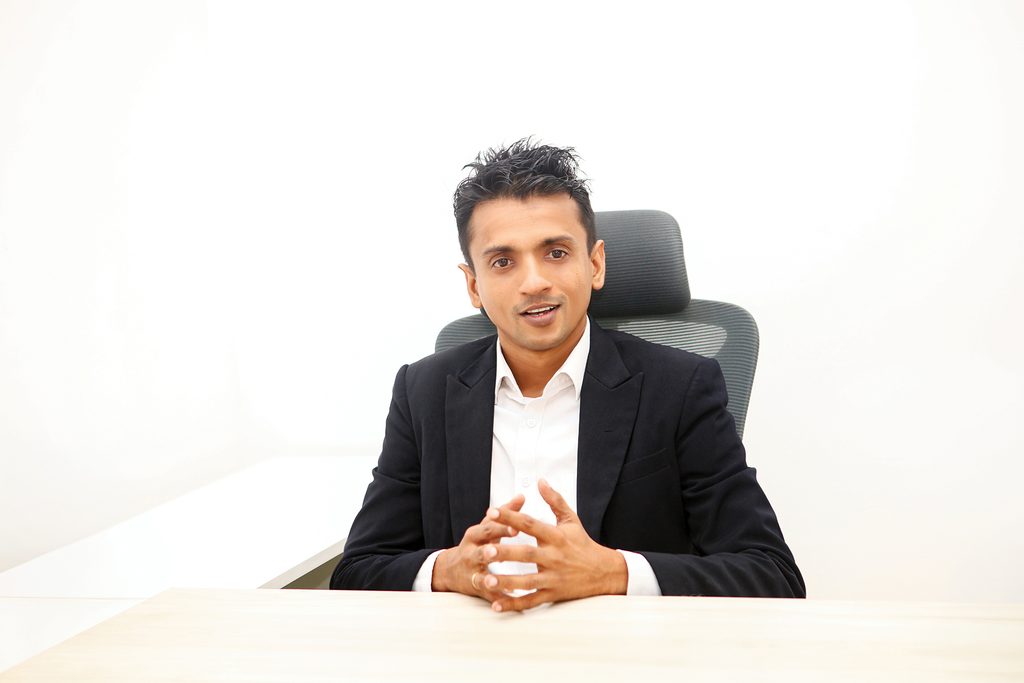
Dhananath Fernando, CEO and founding member, Advocata Institute.
Sri Lanka’s transition from economic stabilization to sustained growth will depend on its willingness to undertake difficult structural reforms, says Dhananath Fernando, CEO and one of the founding members of Advocata Institute.
Speaking with Business Today, he sets out the priorities – integrate with global markets, reduce the cost of doing business, reform State-owned enterprises, strengthen institutions, and create an environment in which private investment can drive productivity and exports. He cautions that without addressing these underlying constraints, the country risks returning to a crisis.
Fernando’s perspective is shaped by a career that took an unconventional route into economics. Trained in bioscience and biochemistry at the University of Colombo, he developed his understanding of economics through independent research, reading, and professional experience. His time at MAS Holdings introduced him to manufacturing and global operations, while his subsequent work at Breakthrough Business Intelligence deepened his understanding of the relationship between economics and marketing. In 2016, he co-founded Advocata Institute, a public policy think tank focused on economic reform, deregulation, State-owned enterprise reforms, debt sustainability, and international trade.
Words: Jennifer Paldano Goonewardane.
Photography: Rasanga Dissanayake and Sujith Heenatigala.
Sri Lanka has made considerable progress in restoring macroeconomic stability following the economic crisis. How would you assess the economy’s current position, and to what extent has the recovery translated into a stronger economic foundation rather than a temporary rebound?
The economy is stable, and key indicators support this. Container shipments, electricity generation, and the Purchasing Managers’ Index all point to economic stability. Inflation also remains in single digits, although the target is five percent. However, stability alone is not enough.
In my view, five key reforms have helped establish a stronger foundation than in previous recoveries. These are the Public Debt Management Act and the establishment of the Public Debt Management Office; the Public Financial Management Act, which limits government expenditure to 13 percent; the Anti-Corruption Act; the Central Bank Independence Act, which restricts monetary financing; and the fuel pricing formula, although the latter has not been implemented as intended.
These reforms have introduced mechanisms and legal frameworks that make it more difficult to reverse course overnight. They provide a basis for managing public debt, controlling government spending, strengthening accountability, and maintaining monetary discipline.
However, these five reforms represent only the minimum foundation required to maintain stability. Much more needs to be done to build an economy capable of sustaining growth. Without growth, stability itself may not last. As the saying goes, stability is not everything, but without stability, everything is nothing. Sri Lanka has achieved a degree of stability; the next challenge is to translate it into sustained economic growth.
This requires strengthening the existing reforms while building the institutions needed to support a competitive, investment-driven economy. For example, the fuel pricing mechanism needs to be improved to better reflect international market prices, with stronger regulation of private operators. Investment in fuel storage infrastructure, involving the Ceylon Petroleum Corporation and other market participants, would also help the country absorb external price shocks. Similarly, the Public Debt Management Office needs greater technical capacity and the expertise required to manage the country’s debt effectively. Fiscal management must also be strengthened to ensure that expenditure remains within established limits.
Beyond these measures, Sri Lanka needs institutions that can support trade, investment, and productivity. A dedicated trade office could help connect local businesses with global supply chains, while the current Board of Investment structure needs reform to attract greater foreign direct investment. FDI remains below one percent of GDP, and inflows have struggled to exceed USD one billion to USD 1.5 billion annually over the decades. Reforming the BOI, including through elements of the Economic Transformation Act, could help address this weakness.
Other priorities include establishing a productivity commission, a competition commission, and a dedicated trade negotiation office. Bankruptcy laws also need reform. While Sri Lanka aspires to become a hub for startups and innovation, businesses must be able to exit the market efficiently when they fail. At present, closing a company can be more difficult than incorporating one.
A clear and efficient insolvency framework would allow entrepreneurs to resolve business failures and redirect resources towards new ventures.
Factor market reforms are equally important. Land, labor, and capital must be more accessible if businesses are to expand and productivity is to improve. Around 82 percent of Sri Lanka’s land is government-owned, while approximately 95 percent of BOI industrial zones are already occupied. The remaining land is often in locations with limited access to ports and airports. Digitally mapping available industrial and private land could improve access, unlock investment, and make it easier for businesses to identify suitable locations.
Labor regulations also need to be modernized. Restrictions affecting women’s employment, including provisions governing night work, can limit labor force participation. Reform must be accompanied by appropriate enforcement and safeguards. Access to capital is another concern, as collateral requirements and restrictions in banking and capital markets limit businesses’ ability to obtain financing. Regulatory barriers that make it difficult to establish and operate businesses must also be addressed.
Without reforms that improve productivity, attract investment, strengthen competition, and connect businesses to global markets, the economy risks remaining stable without generating sufficient growth. In that situation, another external shock could push the country back into crisis, making recovery even more difficult.
Sri Lanka has achieved a degree of stability; the next challenge is to translate it into sustained economic growth.
How would you assess Sri Lanka’s capacity to attract and retain the talent needed to manage these institutions effectively, and what public sector reforms are necessary to address the shortfall?
Sri Lanka’s capacity is very limited at both the political and bureaucratic levels. Politically, there is a shortage of people with the public policy expertise and exposure needed to navigate complex global challenges. Within the public service, low salary scales make it difficult to attract and retain qualified professionals. The regulatory framework also restricts the recruitment of suitable talent from overseas, creating a cycle in which institutions lack the expertise needed to perform effectively.
The structure of the public sector compounds this problem. A disproportionate share of the salary bill goes towards the lower levels of a top or bottom-heavy workforce, leaving little room to offer competitive salaries to senior professionals and specialists. Increasing salaries across the existing structure would impose a substantial additional burden on taxpayers. Consequently, the government struggles to attract the talent required to build institutional capacity.
However, bringing professionals from the private sector into government is not, by itself, a solution. Managing a public institution requires different capabilities, and the private sector itself faces capacity constraints. Repeated appointments of private sector professionals to government boards have not necessarily improved performance, with some institutions continuing to incur losses. Individual appointments cannot deliver results without capable teams, appropriate remuneration, and a regulatory framework that allows institutions to recruit the right people.
This is why public sector reform must begin with a management audit to identify inefficiencies and determine where the workforce can be rationalized. A voluntary retirement scheme (VRS) could provide an exit option for surplus staff, reducing the cost of lower-level staff and creating fiscal room to pay competitive salaries to senior professionals and specialists. The objective should be to restructure the workforce so that savings can be redirected towards building the expertise required to run institutions effectively.
Reform is also becoming increasingly urgent because of the long-term pension challenge. While the pension system remains sustainable at present, population aging and rising retirements could make it fiscally unsustainable over time. Addressing this early would be preferable to waiting until the government faces a crisis, particularly given the political difficulty of implementing pension reforms.
The five reforms that helped restore macroeconomic stability are insufficient to sustain economic stability over the long term. Sri Lanka must now address public sector capacity, pension sustainability, and institutional weaknesses. Without these reforms, it will be difficult to attract the talent needed to manage public institutions effectively and sustain economic stability.
Do you think there has been a long-standing pattern of political patronage and conflicts of interest influencing appointments to State institutions, and how does this affect their effectiveness?
Appointments to State institutions can sometimes be linked to political support, including financial contributions to election campaigns. I am not suggesting that all appointments are made on this basis, or that everyone who contributes to a campaign is unqualified. However, there can be a reciprocal relationship in which businesses receive regulatory advantages and, in return, those who support political campaigns are appointed to positions once the government comes to power. It becomes a case of mutual benefit, where each side protects the other.
The private sector has also become a major beneficiary of the government’s extensive role in the economy. Businesses and the State can become dependent on each other, rather than allowing the market to function through competition. This is an unfortunate situation because the government’s primary role should be to establish and enforce regulations, ensuring a level playing field in which businesses compete on their merits.
When political relationships influence appointments and regulatory decisions, the distinction between the regulator and the businesses it oversees becomes blurred, undermining competition and weakening the institutional framework needed for a well-functioning economy.
Without reforms that improve productivity, attract investment, strengthen competition, and connect businesses to global markets, the economy risks remaining stable without generating sufficient growth.
Public sector reforms can be politically costly and difficult to implement. When should a government undertake these reforms, and why is timing so important?
These reforms are painful, which is why I believe they should be undertaken early in a government’s term, ideally within the first 100 days or, at the latest, the first year. At that stage, a newly elected government is more likely to have the public support needed to implement difficult decisions. As the next election approaches, political pressures make such reforms increasingly difficult.
The reality is that these reforms will eventually have to happen. Sri Lanka’s debt problem had been building for years before the country reached a point where debt restructuring became unavoidable. We all witnessed how painful that process was. The choice is whether to begin reforms early or wait until the system reaches a breaking point.
Unfortunately, governments often postpone reforms during their first two years and attempt to implement them later, when they recognize that the existing system is unsustainable. By then, electoral pressures can make meaningful change difficult. This is why governments should use the early part of their term to undertake the necessary reforms rather than wait for another crisis to force their hand.
Local and international businesses have been invited to invest in Sri Lanka, citing commitments to transparent governance, sound regulation, and essential infrastructure, as well as a regulatory framework designed to protect investments and remove administrative bottlenecks. What would constitute credible evidence that there is a meaningful change in the investment climate?
There may be a growing perception that corruption has declined, which is a positive development. However, the real test of a meaningful improvement in the investment climate is whether Sri Lanka has become more competitive. Investors are not simply looking for assurances of transparent governance; they need an environment in which they can operate efficiently, access resources and markets, and earn competitive returns.
One way to assess progress is to examine the nature of foreign direct investment (FDI). Much of the investment we see comes from existing foreign companies reinvesting their profits to expand their operations. Reinvestment is valuable, but it should not be confused with attracting new investors. We need to see substantial new investments that demonstrate confidence in Sri Lanka as a destination.
The problem is that we are competing with countries such as India and Vietnam, which offer more attractive investment ecosystems. Southern Indian states, for example, have growth rates of around eight to nine percent and have attracted major manufacturers, including Foxconn and suppliers serving Apple. Recruiting employees and navigating regulations can also be easier in these markets. India’s trade agreements with the European Union, the UK, and other countries provide preferential access to a much wider range of markets. Sri Lanka’s more limited market access is a disadvantage when investors decide where to locate their operations.
Our cost structure is another major obstacle. Research by Advocata Institute indicates that Sri Lanka’s construction costs are exceptionally high relative to local income levels and international benchmarks. Materials such as steel, wall and floor tiles, aluminum, and cement can cost around 40 percent more than in competing regional markets. These costs affect everything from hotels to logistics centers and warehouses.
Consider a hotel project. An investor may commission an attractive design in steel and glass, but when costs are evaluated, the same project could be built substantially more cheaply in Thailand or Mumbai. The higher capital expenditure must eventually be recovered through room rates, making the hotel less competitive. This helps explain why Sri Lanka has seen few major new hotel projects following Cinnamon Life, with much of the activity concentrated on renovations. The same cost disadvantage affects other sectors.
Sri Lankan businesses face these constraints too. Some are expanding into markets such as Africa, Vietnam, Bangladesh, and India because they find it easier to grow their operations there. If local businesses struggle to expand in Sri Lanka, international investors are likely to encounter similar barriers.
Therefore, credible evidence of a changing investment climate must include easier access to land, better digital connectivity, efficient logistics, improved transport links, simpler regulations, and lower operating costs. Investors need to see measurable improvements in these areas, alongside increased new investment.
Anti-corruption is a basic requirement. Serious investors expect transparent governance as a matter of course. Furthermore, excessive regulation and administrative restrictions can create opportunities for corruption by encouraging businesses to circumvent cumbersome procedures. Reducing these barriers is therefore essential.
Individual appointments cannot deliver results without capable teams, appropriate remuneration, and a regulatory framework that allows institutions to recruit the right people.
Sri Lanka has long identified exports as a growth priority, yet export diversification and expansion have remained challenging. Is the problem primarily the cost of doing business, trade policy, limited market access, regulatory uncertainty, or the country’s inability to attract investment into competitive industries?
The problem is a combination of all these factors. Market access is a significant constraint. For example, an Indian company previously operated a manufacturing facility in Sri Lanka to export to the UK, taking advantage of Sri Lanka’s GSP+ trade preferences while India lacked equivalent access. Now that India has signed trade agreements with the UK and the European Union, the company can manufacture in India at a lower cost and access those markets directly. Sri Lanka’s limited network of trade agreements puts us at a disadvantage. We have agreements with India and Pakistan, while the status of other negotiations, including those with Singapore and Thailand, remains uncertain. Countries such as Vietnam have established a much wider network of trade agreements, giving their exporters preferential access to international markets.
However, exports cannot grow without investment. Exporters are not limited to Sri Lankan businesses producing locally; foreign investors also establish operations here to manufacture and export. Our solid tire industry, in which Sri Lanka is a global leader, and seafood exports demonstrate the importance of investment in developing competitive export sectors. Without attracting new investment, it will be difficult to expand existing industries or diversify into new ones.
Regulatory barriers are another major obstacle. Customs procedures remain cumbersome, and the Customs Ordinance is outdated. We must also recognize that exports depend on imports. Exporters need access to imported raw materials, components, and specialized inputs to meet international quality and production requirements. The apparel industry, for instance, imports substantial quantities of materials to manufacture products for global brands such as Nike and Victoria’s Secret. A country cannot become a competitive exporter if its producers face restrictions and delays in importing essential inputs. Vietnam illustrates this relationship: its exports and imports are each in the region of USD 400 billion, reflecting the role of imported inputs in supporting export-oriented production and its position in global supply chains.
The choice is whether to begin reforms early or wait until the system reaches a breaking point.
The wider regulatory environment makes it difficult to establish and operate businesses. Through a project with the Western Province, we examined the process of registering sole proprietorships and partnerships. The required documentation can be extensive, including certified identification, rental agreements, and address confirmations with the Grama Niladhari and the Divisional Secretariat. Collecting and submitting these documents can take more than three weeks. In some respects, registering a limited liability company can be easier than registering a sole proprietorship, which indicates how cumbersome the system has become.
Our analysis of the investment approval process found that a foreign investor may need around 16 regulatory clearances, some of which depend on prior approvals. Depending on the industry, obtaining them can take 18 months to two years. Few investors will be willing to wait that long when competing destinations offer a more efficient process.
Access to land presents a similar challenge. Investors can find themselves navigating multiple agencies because land may fall under the authority of the central government, provincial councils, local authorities, the Road Development Authority, or the Department of Archaeology. Securing the necessary clearances becomes a lengthy and uncertain process.
The mineral sands sector provides a further example. An investor that reportedly committed around USD 18 million in 2012 has faced prolonged uncertainty over environmental licensing. After obtaining a license, the company was informed that the license was invalid and that another was required. A further license was obtained in 2016, yet the matter remained unresolved in 2026, with the relevant authority considering cancellation. Such cases demonstrate how regulatory uncertainty can undermine investor confidence and put long-term investments at risk.
Sri Lanka can build on established export sectors such as apparel, tea, coconut, rubber, and seafood, while expanding IT services and shipping. However, their growth remains constrained by the same underlying problems. Successive governments have promoted exports through national strategies, committees, exhibitions, diplomatic missions, and investor delegations, but these efforts cannot compensate for weaknesses in the fundamentals.
We need to address market access, investment barriers, regulatory inefficiencies, and the functioning of factor markets. The global business environment changes rapidly, and investors need certainty, efficiency, and the ability to operate competitively. Inviting prominent investors to Sri Lanka will not resolve these issues. Even a major investor such as Elon Musk would face the same obstacles unless the system changes. Creating special channels to fast-track selected investors is not a sustainable solution either, as it could create opportunities for preferential treatment and corruption.
Sri Lanka must fix the underlying policy and regulatory framework. Without that, export strategies and investment promotion will continue to yield limited results, regardless of how much effort is devoted to attracting businesses to the country.
What prevents successive governments from dismantling fragmented regulations and establishing a coherent policy framework? Is it a lack of technical expertise, vested interests, or political will?
There are several reasons. First, regulatory barriers often create opportunities for certain individuals and groups to benefit from the existing system. Those who benefit are naturally reluctant to give up these advantages. Although reform may create new opportunities for others, there is resistance to relinquishing established benefits.
Second, policymakers often lack a sufficient understanding of the policy issues and the technical expertise needed to design effective regulatory frameworks. The gambling and gaming industry is a good example. We believe it could become a growth sector, potentially generating more than USD one billion in revenue if properly regulated. I am not advocating gambling, but if Sri Lanka intends to develop this industry, it needs an appropriate regulatory framework.
We have attracted Melco, a globally recognized operator that has invested more than USD 100 million in Sri Lanka. However, the absence of an effective gambling regulator and the delay in gazetting the relevant regulations have created uncertainty. The company must comply with international standards across its operations, including those in Macau and Hong Kong, but without effective local regulation, it cannot compete on a level playing field. It is therefore constrained in how it can operate, leaving it with limited options, potentially including exiting the market.
Advocata Institute conducted a detailed study on the establishment of a gambling regulatory authority and presented its findings to the Committee on Public Enterprises (COPE).
We argued that the proposed framework was inadequate and recommended drawing on established models, such as Singapore’s legislation, adapting them to Sri Lanka’s requirements rather than attempting to develop everything from scratch. However, the recommendations were not acted upon as we had hoped.
The consequences extend beyond lost investment. Weak regulation has contributed to problems involving junket operators, online gambling, and alleged scam operations based in Sri Lanka targeting the Filipino market. Such activities can raise broader concerns, including money-laundering risks and distortions in the property market. Without a proper understanding of the industry and its regulatory requirements, policymakers end up responding to problems as they arise rather than preventing them. This illustrates the broader challenges facing reform-limited policy expertise, inadequate institutional capacity, incentives to preserve the status quo, and a lack of political will. Although the need for reform may be widely recognized, implementing it is another matter.
Political considerations are particularly important because structural reforms are rarely popular in the short term and may cost a government votes. This is why I believe reforms should begin within the first 100 days of a new government, or at least during its first year. Early action gives the government time to implement changes and demonstrate their benefits before the next election.
If reforms lead to greater investment, business expansion, and job creation, the government can show voters that difficult decisions have delivered results. When reforms are postponed until an election approaches, however, political incentives discourage action, while the benefits may take too long to materialize within that electoral cycle.
Investors are not simply looking for assurances of transparent governance; they need an environment in which they can operate efficiently, access resources and markets, and earn competitive returns.
What changes to the tax system would make it more predictable, equitable, and supportive of long-term investment while ensuring that the government can fund essential public services?
A sound tax system should adhere to four basic principles: transparency, simplicity, neutrality, and consistency. Taxpayers should understand what they are paying, how the system works, and how the revenue is used.
However, Sri Lanka’s tax system remains complicated, making it difficult for individuals to calculate their own taxes and often requiring them to seek professional advice. For example, the multiple income tax brackets, ranging from six to 36 percent, add to this complexity.
Tax neutrality is equally important. The government should not selectively impose taxes on certain groups or grant exemptions to others, as this distorts competition.
Consistency is another weakness. Changes to the VAT registration threshold and the Advance Personal Income Tax (APIT) have created uncertainty, making it difficult for individuals and businesses to plan their finances and investments.
In my view, the tax system should be simpler and progressive, with fewer tax brackets. Excessive complexity encourages tax avoidance and makes compliance more difficult. I would also favor a broader VAT base rather than placing too much reliance on corporate and personal income taxes. VAT is collected when a transaction takes place, meaning consumers pay tax when they purchase goods and services. Those who consume more generally contribute more in absolute terms. By contrast, income tax is deducted from salaries even before individuals decide how to spend their earnings.
I recognize that extending VAT to a wider range of goods and services may not be popular, but broadening the base would help create a more level playing field. Consider poultry products: chicken sold through supermarkets is subject to VAT, whereas similar products sold at traditional markets may not be. This puts formal businesses, including those with the capacity to export, at a competitive disadvantage. The same applies across the wider protein market, where fish and poultry may face different tax treatment. A more neutral system would reduce these distortions and support businesses investing in productivity and export capacity.
Differential taxation of fuel provides another example of how tax policy can encourage inefficient practices. Diesel, which is used by trawler boats, is taxed differently from kerosene, making kerosene relatively cheaper. This can discourage the use of more productive fishing methods and encourage less efficient alternatives. Similarly, some buses use kerosene instead of diesel due to the price difference resulting from taxation. These examples illustrate how tax differences intended to benefit particular groups can produce unintended consequences.
A simpler, more consistent, and neutral tax system would reduce market distortions, improve compliance, and give businesses greater certainty when making long-term investment decisions. By broadening the tax base and ensuring fair treatment across sectors, the government can generate the revenue needed to fund essential public services while supporting productivity and economic growth.
Sri Lanka must fix the underlying policy and regulatory framework. Without that, export strategies and investment promotion will continue to yield limited results.
The proposed AI center signals an ambition to position Sri Lanka within the emerging AI economy. What economic purpose should such a center serve, and how should the government measure its success beyond the establishment of the facility itself?
An AI center could help Sri Lanka participate in the emerging AI economy, but its success will depend on the broader ecosystem that supports it. The first consideration is energy cost. Data centers consume enormous amounts of electricity, so Sri Lanka must make energy more affordable to attract investment. The country has considerable potential for renewable energy, given its access to solar and wind resources. However, unlocking this potential requires upgrading the electricity grid, which will need private investment.
The second consideration is skills. Sri Lanka has a reasonable IT workforce, but attracting and operating advanced AI facilities requires specialized expertise. Labor regulations should therefore be made more flexible to enable the recruitment of foreign AI professionals, building on existing provisions available through the BOI.
AI investment is worthwhile, and Sri Lanka should pursue it. However, success should be measured by its ability to attract investment and expertise, supported by affordable energy, reliable infrastructure, and the skills needed to compete in the global AI economy.
The government intends to open electricity transmission to private investment. What model would allow private capital to participate without creating private monopolies or imposing high costs on electricity consumers?
Electricity generation and distribution are already open to private investment, as reflected in tenders for solar, wind, and other power projects. The main challenge is transmission, where the grid remains state-owned and requires substantial investment to accommodate additional renewable energy. Without upgrading the grid, excess solar generation during the day can overload it, forcing solar plants to curtail production. This limits renewable energy expansion and the potential to reduce electricity costs.
There are several ways to bring in private capital without creating private monopolies. One option is to tender specific sections of the grid to different companies, with clear investment, performance, and regulatory requirements. However, building competing transmission networks would be expensive, as the grid must function as a shared facility.
Another model is to establish a separate company in which the government remains a major shareholder and private investors hold minority stakes. This would allow private capital to fund grid upgrades while sharing the returns generated through the electricity supply chain. Appropriate regulation would be essential to ensure fair access and prevent high costs to consumers.
The principle is that neither a state monopoly nor a private monopoly is desirable. Although the sector has been unbundled into separate state-owned companies, private investors need a meaningful opportunity to participate as stakeholders. Bringing in capital and improving efficiency are essential to modernizing the transmission grid, expanding renewable energy, and ultimately lowering electricity costs.
The current Extended Fund Facility (EFF) with the IMF ends in March 2027. How should Sri Lanka decide whether to enter into a follow-up IMF program after March 2027? What objective economic conditions should determine that decision, rather than political considerations or public perceptions of the program?
The decision to enter into another IMF program after March 2027 should be based on debt sustainability, access to international capital markets, and the global economic outlook, rather than political considerations. The IMF has helped Sri Lanka stabilize its economy over the past three and a half years, and the remaining six months of the current program should be used to consolidate that progress.
A key consideration is Sri Lanka’s ability to borrow from international markets at sustainable interest rates. This depends partly on its credit ratings. So far, only Fitch has upgraded Sri Lanka to B−, while Moody’s and S&P have not followed suit. A stronger rating, ideally reaching B+, would improve market access and borrowing terms. Continued engagement with the IMF could support investor confidence by providing external oversight and reducing concerns about politically driven policy reversals. IMF financing, at around four to five percent in the current context, may also be cheaper than market borrowing at around eight to nine percent.
However, the IMF primarily focuses on stabilization, and its conditions may not be sufficient to drive economic growth. It is more like a lifeguard than a swimming coach – it can help prevent another crisis, but it cannot teach a country how to build a stronger, more productive economy.
Given that institutional development and factor-market reforms remain incomplete, I would consider another IMF program to help maintain policy discipline and reduce the risk of returning to a debt crisis. However, the government must also develop and implement its own reform agenda to address the structural barriers to investment, productivity, and growth. The IMF cannot make Sri Lanka prosperous; that requires sustained domestic reforms and political commitment. The decision should therefore reflect whether another program would help preserve stability while supporting a credible, locally owned path to long-term growth.
SriLankan Airlines remains a difficult policy choice. What should be the Government’s primary objective for the airline: commercial viability, national connectivity, tourism development, or some combination of these?
In my view, the Government should prioritize resolving SriLankan Airlines’ financial problems rather than continuing to subsidize its operations. The airline is burdened by substantial liabilities, making a turnaround difficult without a serious investor. Even if an investor can be found, taxpayers may first have to absorb billions of dollars in accumulated obligations. The previous government absorbed around USD 500 million, yet the airline remains dependent on Treasury support. The Auditor General has also highlighted that it cannot continue as a going concern without such assistance. A substantial portion of the airline’s debt is owed to State banks, which cannot indefinitely absorb these losses. If SriLankan Airlines cannot repay its borrowings, the Treasury may have to step in to protect the banks’ balance sheets, ultimately placing the burden on taxpayers. In the latest budget, 20 billion rupees were allocated to the airline, with a further 20 billion reportedly under consideration. Of the 41 billion rupees in subsidies discussed, 25 billion was allocated to SriLankan Airlines alone. This is not a sustainable model, particularly when the benefits of subsidizing air travel largely accrue to those who can afford to fly.
The airline’s difficulties are also connected to wider distortions among State-owned enterprises. Government fuel subsidies contributed to losses at the Ceylon Petroleum Corporation (CPC), which supplies aviation fuel to SriLankan Airlines. According to this account, CPC charged the airline excessively for jet fuel to recover losses incurred elsewhere, including supplying fuel to the Ceylon Electricity Board at concessional rates. The airline consequently faced high operating costs and borrowed heavily from State banks, creating a cycle of losses and public liabilities.
Nor is retaining the airline essential to sustaining tourism. Although SriLankan Airlines accounts for around 23–27 percent of tourist arrivals by air, more than 70 percent arrive on other airlines. Other carriers could take up some of the demand if SriLankan Airlines were restructured or its operations changed. An alternative would be to retain the SriLankan brand while bringing in a private investor or appointing an experienced operator under a management contract, as was done previously with Emirates. However, the way that the earlier arrangement ended may make investors cautious about future government intervention. There are also opportunities to improve competition at Bandaranaike International Airport. SriLankan Airlines has a strong safety record and an established catering operation, while its catering and ground-handling services operate as monopolies. Opening these services to competition could improve choice and make the airport more attractive to other airlines.
The airline’s operational challenges further reinforce the need for reform. Aviation is a highly competitive business requiring timely decisions and continuous investment in maintenance, equipment, and service improvements. The Government’s limited capacity to fund these needs has contributed to repair-related delays, affecting passenger confidence and potentially weakening demand. The Airbus corruption scandal adds another dimension. European Union court proceedings referred to an expected bribe of USD 16 million, of which USD two million was reportedly received, while the broader aircraft arrangements were estimated at around USD 200 million. Subsequent leasing decisions and the cancellation of an agreement resulted in further losses that may be difficult to recover.
The Government has appointed a committee to examine restructuring, but the process will be difficult. In my view, the objective should be to remove the airline’s unsustainable burden on taxpayers while exploring private investment and options for retaining the SriLankan brand. The priority must be a financially viable operating model that protects public finances, strengthens competition, and allows the airline’s commercial future to be determined on a sustainable basis.
In terms of State-owned enterprise reform, should the Government adopt a transparent framework that classifies state-owned enterprises into those to be privatized, commercially restructured, retained for strategic reasons, or closed? What should determine these decisions?
The Government is planning to establish a State-Owned Holding Company under which all State-owned enterprises (SOEs) would be placed. This would function like a corporate holding company, with its own board overseeing the group and individual boards managing each enterprise.
Rather than decisions being made by ministers, the holding company would provide a central structure for determining each SOE’s future. This approach was also recommended in the IMF’s Governance Diagnostic Report.
Within this framework, the Government could decide which enterprises to privatize, commercially restructure, retain for strategic reasons, or close. These decisions should be based on commercial viability, strategic importance, and the need to reduce the recurring burden on public finances, supported by transparent governance and accountability.
In my view, the holding company is a positive step. Ideally, Sri Lanka could have pursued privatization more extensively, provided the necessary governance safeguards were in place. However, some enterprises will require commercial restructuring, while others may warrant retention for strategic reasons.
Without a clear framework and decisive action, the country risks continuing the cycle of SOE losses and repeated reliance on taxpayer support.
How can Sri Lanka build the public support and political momentum needed to implement difficult economic reforms, particularly when policymakers and vested interests are reluctant to act?
The way forward is to build pressure for reform from the bottom up. We cannot rely solely on policymakers or the private sector to drive change, as both may lack the capacity or incentives to do so. Some businesses also focus primarily on their own interests rather than on broader economic reform. Improving public economic literacy is therefore essential. When people understand why reforms are necessary and demand change, resistance can diminish, and policymakers face greater pressure to act.
Sri Lanka’s experience shows how crises can create the conditions for reforms that were previously unpopular. Fuel pricing formulas, for example, faced considerable resistance when attempts were made to introduce them in 2000, 2018, and under the Gotabaya Rajapaksa administration. Following the economic crisis, the need for more realistic fuel pricing became widely accepted. Similarly, opening the fuel market to new private operators, beyond Lanka IOC’s 2003 entry, became more feasible after the crisis. Electricity sector reforms also gained momentum after prolonged power cuts exposed the costs of maintaining the existing system.
These changes illustrate how public pressure can overcome resistance from political interests and powerful groups, including trade unions. However, reforms introduced under crisis conditions may not always take the ideal form. The objective should be to build public understanding and support before another crisis forces action. Without stronger public demand, political commitment, and broader recognition of the need for change, Sri Lanka risks repeating the cycle of delaying reforms until economic conditions deteriorate.
To what extent does the private sector share responsibility for corruption and the lack of progress on economic reforms, and how do weaknesses in the regulatory system contribute to the problem?
The private sector certainly shares responsibility for corruption; it takes two parties to engage in it. However, we must also recognize that policy and regulatory bottlenecks can create incentives for corrupt practices. When an investor must obtain up to 16 regulatory approvals to establish a business, the system creates opportunities for bribery.
In many cases, investors say they are not paying bribes to do something illegal, but to expedite a process they are legally entitled to complete. That does not absolve the private sector of responsibility, as paying a bribe remains wrong. However, when excessive regulations and delays make legitimate business activity difficult, some may resort to such practices to get things done. Therefore, addressing corruption requires accountability from both the public and private sectors, as well as reforms that streamline approvals, remove unnecessary barriers, and make regulatory processes more transparent and efficient.
To what extent has the private sector resisted trade liberalization and other reforms that could improve competition, lower costs, and benefit the wider economy?
Some businesses have prioritized their own interests over the wider economy, resisting reforms that would increase competition, including free trade agreements. Such resistance contributes to the high costs of construction, electricity, and other goods and services, while limiting improvements in public transport and market efficiency.
However, regulatory barriers have also shaped this behavior by protecting established interests and making competition more difficult. The private sector is therefore partly responsible for the high costs and inefficiencies that consumers face, although not all businesses contribute to this culture. Meaningful reform requires both the removal of unnecessary regulatory barriers and a willingness among businesses to compete in a more open market, rather than resist changes that threaten their existing advantages.
How serious is the risk that migration of skilled workers will weaken Sri Lanka’s long-term growth potential?
The risk is significant, particularly because skilled migration is taking place alongside a major demographic shift. Sri Lanka’s child population is contracting, while an estimated 1.8 million young people aged 17–21 are expected to enter the labor force over the coming years, according to recent figures from the Census and Statistics Department. The country must create enough productive jobs for this generation or risk losing more of its talent overseas. At the same time, the population is aging, increasing future demand for healthcare and elderly care.
The profile of migration has also changed. Whereas migration was once associated largely with women taking up domestic work overseas, skilled young men are now leaving for destinations across the Middle East and Europe. An estimated 50,000–70,000 people migrate annually. Although their remittances support the economy, the departure of experienced, mid-level professionals is making it harder for Sri Lankan businesses to recruit and retain talent.
The consequences could become more severe over the next 10–15 years, when an aging population will require more people to provide care, at a time when the domestic workforce may be shrinking. Sri Lanka must therefore address the underlying reasons people leave by improving productivity, remuneration, career opportunities, and the overall business environment. Without faster reforms, the country risks weakening its long-term growth potential while struggling to meet the needs of its own aging population.
What lessons should Sri Lanka draw from countries that have successfully moved from middle-income status towards more productive export-oriented economies? Which lessons are realistically applicable to Sri Lanka’s circumstances?
The first lesson is the importance of global integration. Countries that have achieved higher per capita incomes have done so by integrating with international markets and expanding exports. Sri Lanka must similarly open its economy, secure better market access, and connect local businesses to global value chains.
Second, production costs must become internationally competitive. Electricity, raw materials, land, labor, and construction costs affect businesses across every sector. High costs undermine competitiveness throughout the economy.
Third, Sri Lanka needs market reforms that improve access to land, raise labor productivity, and strengthen competition. These reforms would help reduce costs, attract investment, and enable businesses to expand their exports.
Rather than focusing narrowly on which industries the country should promote, Sri Lanka should first address the structural barriers that constrain all businesses. With competitive costs, efficient markets, and stronger global integration, investment can flow into viable opportunities, helping the country progress towards upper-middle-income status and a per capita income exceeding USD 5,000. These are achievable priorities, but they require consistent and timely reforms.
By 2030, what measurable outcomes would convince you that Sri Lanka has genuinely moved beyond crisis management and established a sustainable, private-investment-led growth model?
My first indicator would be a substantial improvement in public transport. An efficient system would make commuting easier, reduce the need to spend foreign exchange on transport-related imports, and improve productivity, supporting businesses, investment, and exports.
Second, I would examine whether port capacity and efficiency have improved to support trade and export growth. Third, I would assess the strength of economic institutions and the effectiveness of reforms, including whether existing institutions are functioning well and whether some should be restructured or closed.
Fourth, I would look at progress in State-owned enterprise reform. The extensive role of SOEs in commercial activities can constrain private investment, so restructuring them and creating a more competitive environment would be essential to a private-investment-led growth model.
These indicators, alongside measures such as export growth, investment inflows, and energy costs, would help establish whether Sri Lanka has moved beyond crisis management towards a more productive, competitive, and sustainable economy by 2030.